Solid Carbide End Mill Trends 2026: Market Growth, Automation and Advanced Coatings
News Details
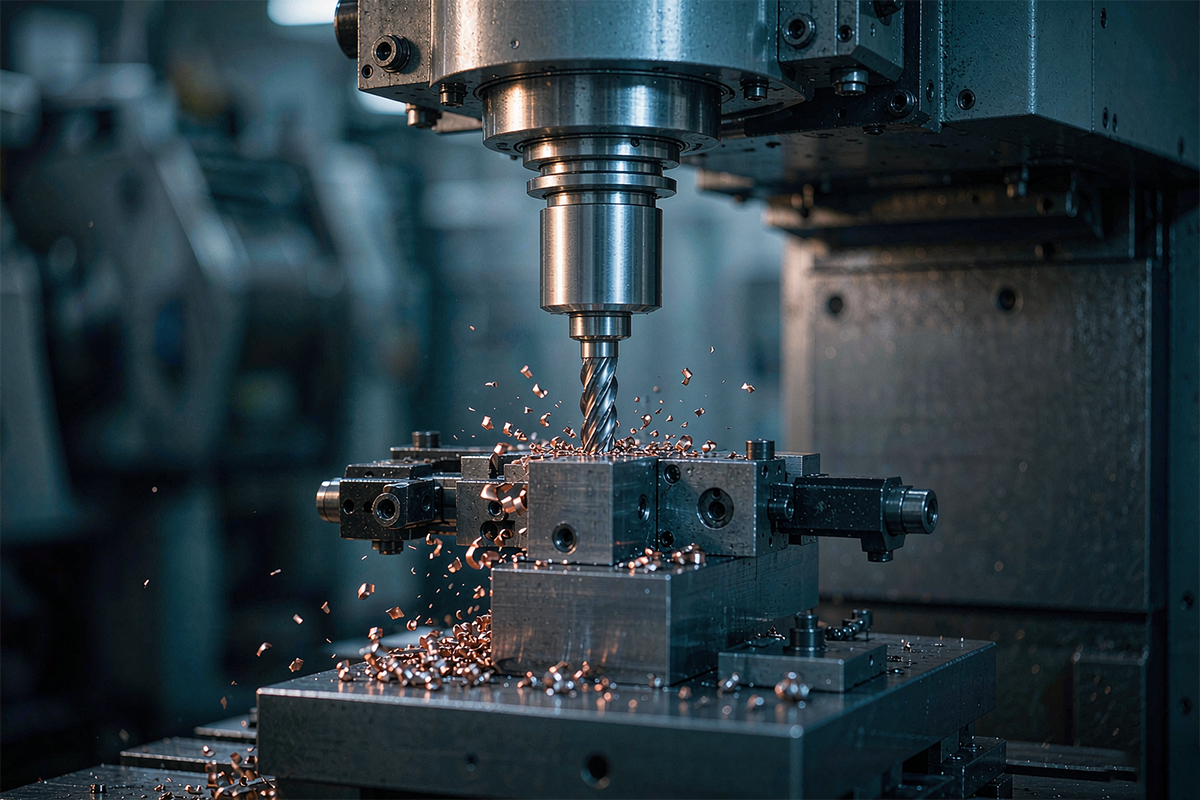
Why Are Solid Carbide End Mills the Focus of Attention in 2026
Solid carbide end mills remain an essential tool in precision milling. For this product category, 2026 represents a year of gradual yet far-reaching structural change. Market research firms predict continued growth at an annual rate of approximately 6 to 7% until 2035, while demand is shifting from general-purpose tooling toward application-specific carbide tooling systems. Three main factors are driving this trend: the widespread adoption of CNC automation, the machining of harder and more heat-resistant materials, and rapid advances in tool coatings and geometries. At the same time, rising tungsten prices are prompting buyers to evaluate tools based on the cost per machined component rather than the purchase price alone.
This industry report summarizes the trends behind these changes and explains what they mean for international buyers of carbide cutting tools.
Market Growth: Stable Expansion Path
Recent market studies generally indicate positive prospects. A 2026 analysis estimates the global solid carbide tools market at approximately USD 14.8 billion in 2026, with a forecast to reach approximately USD 26.5 billion by 2035, representing a compound annual growth rate of about 6.7%. Other research institutions have released similar forecasts, with projected CAGRs generally ranging from 6 to 7%. However, specific market size figures may vary across reports and methodologies.
In terms of product mix, end mills account for the largest market share due to their wide range of applications in CNC machining centers. Coating technology represents the segment with the highest profit margins, and die and mold manufacturing is one of the fastest-growing application areas, driven by the increasing complexity of molds.
CNC Automation Is Reshaping Tool Demand
Automation is the single most significant driver of carbide tool consumption. Market estimates indicate that approximately 63.7% of carbide tooling is used in automated machining, encompassing the automotive, aerospace, machinery, and precision manufacturing industries. As machining centers operate continuously for multiple shifts, the predictability of tool life becomes critical: an unexpected failure of a cutting edge can disrupt the entire automated production line.
This is changing the purchasing philosophy. Manufacturers are increasingly evaluating tool performance based on tool life, cycle time, spindle utilization, scrap rate, and reliability of unattended machining—in other words, based on the cost per finished component rather than the price of the tool itself.
Difficult-to-Machine Materials Are Expanding New Application Areas
Harder alloys and new part designs are continuously expanding the application scope of carbide tools. According to industry research published in early 2026, in the high-performance solid carbide end mills segment, aerospace and defense applications accounted for the largest share of the market in 2025, generating approximately 33.6% of global revenue (about USD 732 million). This was followed by automotive (25.5%), mold and die manufacturing (19.2%), and medical device manufacturing (15.7%).
New end mill grades now offer workpiece hardness capabilities ranging from approximately 50 HRC to nearly 70 HRC, making hardened tool steels and heat-resistant superalloys viable for mainstream carbide milling. The transition to electric vehicles is also changing the mix of machining applications, with battery housings, motor components, and precision molds driving demand for high-speed tools for aluminum and steel.
Technology Trends: More Cutting Edges, Smarter Geometries, Advanced Coatings
High-efficiency machining is the most prominent technological trend in 2026. Manufacturers are increasing the number of flutes on end mills—some new designs feature up to nine flutes, compared to the conventional three to six flutes—and optimizing the helix angle, edge treatment, and chip evacuation. Variable flute geometries and polished flute surfaces reduce vibration during deep-cavity machining and operations with long tool overhangs. Advanced AlCrN and AlTiSiN coatings improve heat and wear resistance, making them ideal for dry machining and minimum quantity lubrication (MQL) processes.
Digital solutions are evolving in parallel. Cutting tool suppliers now offer online parameter calculators, tool selectors, and application databases covering more than 1,000 material conditions, helping operators determine cutting speed, feed rate per tooth, and coolant strategy before the first cut is made.
Pressure on Raw Material Costs and Tungsten Supply
Input costs rose sharply in 2026. Industry analysis from February 2026 reported that tungsten carbide powder prices were approximately RMB 1,750 to 2,060 per kilogram, and 65% black tungsten concentrate was priced at about RMB 735,000 per ton, increasing the production costs of cemented carbide. The global tungsten supply-demand gap is projected to remain above 17% until 2028, as new mining capacity fails to keep pace with demand.
For buyers, this trend further underscores the importance of investing in high-quality tool grades with longer service life, regrinding and recoating services, and selecting suppliers with stable powder sources.
What These Trends Mean for International Buyers
| 2026 Trend | Practical Implications for Buyers |
|---|---|
| Application-specific tooling | When requesting a quotation, clearly specify the workpiece material, hardness, and type of operation to avoid ordering general-purpose tools. |
| Automation-driven demand | Prioritize predictable tool life and consistent batch quality to support unattended production. |
| Advanced coatings | Explicitly specify the type of coating (e.g., AlCrN, AlTiSiN) and request a coating certificate with the shipment. |
| Raw material price fluctuations | Plan inventory of critical tools in advance and consider regrinding and recoating services. |
The market data in this article are estimates from publicly available industry research and may vary by source. They are provided for reference in procurement planning purposes only and do not constitute a guarantee of market conditions.


